A mortgage pre approval UAE banks issue is a conditional letter stating the most they would lend you, over what term, before you have chosen a property. It is not the final approval: the Central Bank of the UAE (CBUAE) requires an independent valuation of the home before any lender commits, and the bank still checks your documents and issues a formal offer letter. Each bank sets its own minimum salary, fees and validity, so the bank figures below come from the banks' own pages, checked on 16 November 2026.
- What limits it: CBUAE rules cap all your monthly debt payments at 50% of gross income, tested at 2 to 4 points above your rate, and finance an expat's first home under AED 5 million up to 80% of its value (UAE nationals 85%; off-plan 50%).
- Validity and cost: Commercial Bank of Dubai (CBD) publishes 60 days and a AED 1,575 fee for salaried applicants; Mashreq lists a AED 1,050 fee. Emirates NBD and ADCB publish neither on the pages we checked.
- Minimum salary: AED 15,000 a month at Emirates NBD (UAE residents) and Mashreq, AED 12,000 at CBD. The Central Bank sets no minimum.
What is a mortgage pre approval, and is it a final approval?
A mortgage pre approval is an approval in principle: the bank looks at your income and debts and states the maximum loan and term it would offer. It is not a final approval. The loan still depends on a valuation of the property you choose, checks on your documents and credit record, and the bank's formal offer letter.
CBD's own FAQ describes it that way: an in-principle approval on the income and liabilities you declare, subject to documents and a formal offer letter. The CBUAE adds the step that most often changes the number: before any irrevocable commitment to lend, an independent valuer must value the property on site. A pre-qualification, such as Dubai Islamic Bank's (DIB) free, document-free First Step Qualified, is lighter still.
| Stage | What the bank looks at | What you get | Does it bind the bank? |
|---|---|---|---|
| Pre-qualification (for example DIB First Step Qualified) | What you tell it | An estimate of what you might borrow | No |
| Pre approval | Your declared or documented income and debts; some banks start from your Emirates ID and online banking | A maximum loan and term, valid for a set period (60 days at CBD) | No: it is subject to valuation, documents and final approval |
| Final offer letter | The valuation, the property's title or developer, all your documents and a credit bureau check | The loan amount, rate, fees and conditions | It leads to the loan contract you sign |
Mortgage pre approval UAE checklist: which documents do banks ask for?
For a salaried applicant, expect your Emirates ID, passport and residence visa, a salary certificate addressed to the bank, three to six months of bank statements and details of any loans or cards. Some digital pre approvals start with less (CBD's needs only your Emirates ID), but the full application asks for all of it.
| Document | What the banks' own pages say |
|---|---|
| Emirates ID, passport and residence visa | Asked for by Emirates NBD, ADCB, Mashreq and CBD |
| Salary certificate addressed to the bank | Emirates NBD and Mashreq; ADCB wants one dated within 30 days of the application |
| Bank statements | Last 6 months at Emirates NBD, ADCB and Mashreq; 3 months for new customers at CBD |
| Payslips | Emirates NBD: the last three months if your salary varies by more than 10% |
| Existing loans and cards | ADCB: details of all liabilities; Mashreq: a liability letter from your bank |
| Proof of the down payment | ADCB: a declaration of where it comes from; Mashreq: down payment receipts |
| Consent to a credit bureau check | CBD: signed with the application form |
| If you are self-employed | Trade licence, memorandum of association, two years of audited accounts and 6 to 12 months of personal and company statements (the exact list differs by bank) |
Two CBUAE rules shape this list. Your down payment must come from your own resources, not from a personal loan or a credit card, which is why banks ask where it comes from. And before granting credit a bank must check your record with the Al Etihad Credit Bureau (AECB). You can see what the bank will see first: AECB sells a personal credit report for AED 84 including VAT, covering the last 36 months.
What is the minimum salary for a mortgage in the UAE?
There is no Central Bank minimum salary for a mortgage; each bank sets its own. On their own pages, Emirates NBD asks UAE residents for at least AED 15,000 a month (UAE nationals AED 10,000), Mashreq starts at AED 15,000, and CBD asks salaried applicants for AED 12,000 with six months in the job.
Age matters too: Emirates NBD and CBD want a salaried expat's loan repaid by 65, Mashreq by 70. At Emirates NBD every borrower on a joint application must meet the minimum salary. The minimum only opens the door; the rules in the next section set how much you can borrow.
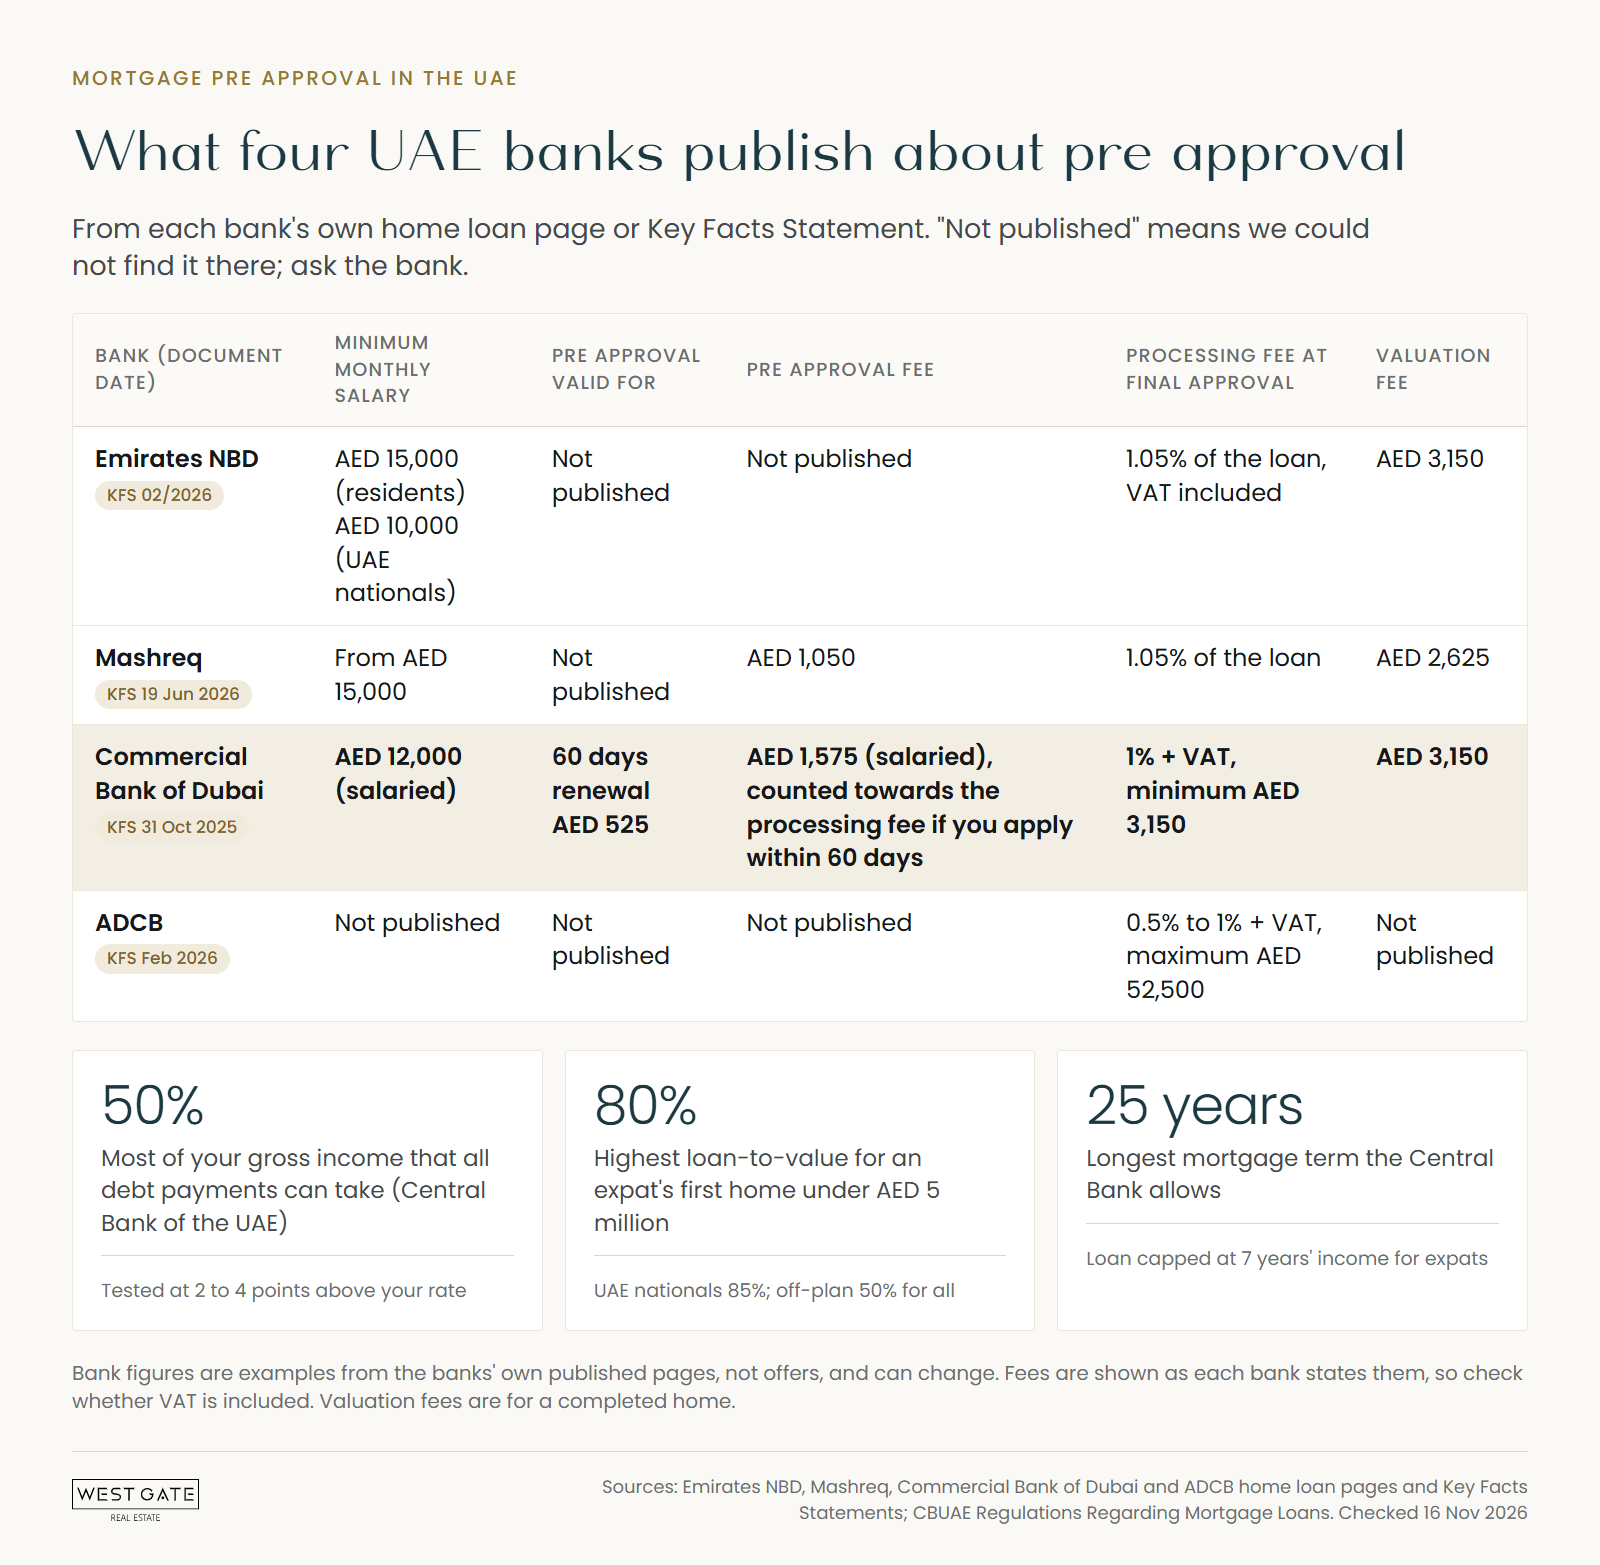
| Bank (document) | Minimum monthly salary | Pre approval valid for | Pre approval fee | Processing fee at final approval | Valuation fee |
|---|---|---|---|---|---|
| Emirates NBD (help page; KFS 02/2026) | AED 15,000 (UAE residents); AED 10,000 (UAE nationals) | Not published | Not published | 1.05% of the loan, VAT included | AED 3,150 (completed home) |
| Mashreq (home loan page; KFS revised 19 June 2026) | From AED 15,000 | Not published | AED 1,050 | 1.05% of the loan | AED 2,625 |
| Commercial Bank of Dubai (pre approval FAQ; KFS 31 October 2025) | AED 12,000 (salaried) | 60 days; renewal AED 525 | AED 1,575 salaried, AED 2,100 self-employed; counted towards the processing fee if you apply within 60 days | 1% + VAT, minimum AED 3,150 | AED 3,150 |
| ADCB (mortgage page; KFS February 2026) | Not published | Not published | Not published | 0.5% to 1% + VAT, maximum AED 52,500 | Not published |
How much can you borrow on your salary in the UAE?
The Central Bank's 50% debt burden ratio (DBR) sets the ceiling: all your monthly debt payments, including the new mortgage tested at 2 to 4 percentage points above its rate, can't exceed half your gross income. An expat also can't borrow more than seven times annual income (UAE nationals eight), and the loan-to-value (LTV) cap sets your deposit.
Here is what those rules allow on four salaries, assuming an illustrative 5.5% rate, a stress test at 7.5% (2 points above, the gentlest end of the range), a 25-year term and an expat's first home under AED 5 million.
| Gross monthly salary | Other monthly debts | Most all debts can take (50%) | Loan ceiling, stressed at 7.5% over 25 years | Home price at 80% LTV | Deposit (20%) |
|---|---|---|---|---|---|
| AED 15,000 | None | AED 7,500 | About AED 1,015,000 | About AED 1,269,000 | About AED 254,000 |
| AED 25,000 | None | AED 12,500 | About AED 1,691,000 | About AED 2,114,000 | About AED 423,000 |
| AED 25,000 | AED 2,000 car loan | AED 10,500 left for the mortgage | About AED 1,421,000 | About AED 1,776,000 | About AED 355,000 |
| AED 40,000 | None | AED 20,000 | About AED 2,706,000 | About AED 3,383,000 | About AED 677,000 |
A ceiling, not a quote The CBUAE tells banks not to apply the 50% limit automatically and to allow for household spending, discount bonuses and test at more than 2 points when rates call for it, so your pre approval can come in lower. At 5.5% itself, the AED 25,000 earner's ceiling loan would cost about AED 10,387 a month. Our mortgage calculator runs your own numbers, and our EIBOR guide explains how variable rates move.
The LTV caps in the CBUAE's Regulations Regarding Mortgage Loans decide the deposit. Banks may ask for a bigger deposit, never a smaller one, and only one property per borrower counts as a first home.
| Buyer and property | Maximum loan-to-value | Minimum deposit |
|---|---|---|
| Expat, first home under AED 5 million | 80% | 20% |
| Expat, first home over AED 5 million | 70% | 30% |
| Expat, second home or investment | 60% | 40% |
| UAE national, first home up to AED 5 million | 85% | 15% |
| UAE national, first home over AED 5 million | 75% | 25% |
| UAE national, second home or investment | 65% | 35% |
| Anyone, off-plan property | 50% | 50% |
Purchase costs come on top of the deposit; our guide to the minimum down payment in Dubai adds them up. If the numbers are tight, compare the monthly cost with renting in our rent vs buy guide.
How long is a mortgage pre approval valid?
CBD states 60 days from the date of issue and charges AED 525 to revalidate a pre approval. Emirates NBD, Mashreq and ADCB don't publish a validity on the pages we checked, and the Central Bank sets none, so read the date on your own letter. Ask for it when you are ready to make offers, not months before.
Leave room for the rest of the deal: after your offer is accepted the bank still values the home and issues the final offer, and Emirates NBD's Key Facts Statement allows up to 10 business days from complete documents to paying out the loan. Renew a letter that is close to expiry before you negotiate, and tell the bank if your salary, job or debts change.
How much does a mortgage pre approval cost?
It depends on the bank. Mashreq's Key Facts Statement lists AED 1,050. CBD charges salaried applicants AED 1,575 and counts it towards the processing fee if the full application follows within 60 days. DIB's First Step Qualified estimate is free. The bigger costs come later: the valuation, the processing fee and the Dubai Land Department (DLD) mortgage registration.
The bank table above lists the valuation and processing fees each bank publishes. At the transfer, DLD charges 0.25% of the mortgage value to register the mortgage, plus AED 250 for the title deed and AED 20 in knowledge and innovation fees. On an AED 1,200,000 loan, a 1.05% processing fee is AED 12,600 and DLD's 0.25% is AED 3,000.
Emirates NBD's Key Facts Statement says its processing fee is non-refundable if you withdraw, so be sure of the property before you pay it. The CBUAE caps some other home loan charges, such as the early settlement fee at 1% of the balance or AED 10,000.
Why does a seller's agent ask for a pre approval before an offer?
Because it shows you can complete. Once a seller accepts your offer, the sale waits on your bank to value the home and issue its final offer. A pre approval shows that a lender has already looked at your income and debts and named a loan amount, so the sale is less likely to stall on finance.
The valuation is the one step a pre approval can't settle. Under the CBUAE's definition, loan-to-value is measured against the appraised value, not the price you agreed. If you agree AED 1,500,000 for a home the valuer puts at AED 1,400,000, an 80% loan is AED 1,120,000 rather than AED 1,200,000, and the cash you need rises from AED 300,000 to AED 380,000. Check the asking price against registered prices per square foot before you offer, and make sure the sale agreement says what happens if the valuation or final approval falls short.
Off-plan works differently. The CBUAE caps any off-plan loan at 50% of the value, and banks add their own conditions: CBD finances homes under construction only from developers on its approved list, and Mashreq's Key Facts Statement asks for the project to be at least 35% complete.
Frequently asked questions
Does pre approved mean approved for a mortgage?
No. A pre approval states the most a bank would lend on the income and debts it has seen. The loan is approved only after an independent valuation of the property, full document checks and the bank's formal offer letter.
How long is a mortgage pre approval valid in the UAE?
It depends on the bank. Commercial Bank of Dubai states 60 days from issue and charges AED 525 to revalidate. Emirates NBD, Mashreq and ADCB don't publish a validity on their pages, so check the date on your letter.
What is the minimum salary for a home loan in the UAE for an expat?
There is no Central Bank minimum; banks set their own. Emirates NBD and Mashreq publish AED 15,000 a month for residents, and Commercial Bank of Dubai publishes AED 12,000 for salaried applicants (checked 16 November 2026).
Does a mortgage pre approval cost money?
At some banks. Mashreq lists AED 1,050 and Commercial Bank of Dubai AED 1,575 for salaried applicants, which it counts towards the processing fee if you apply within 60 days. Dubai Islamic Bank's First Step Qualified check is free.
How much mortgage can I get on my salary in the UAE?
All your debt payments, including the new mortgage tested at 2 to 4 points above its rate, can't exceed 50% of gross income. On AED 25,000 a month with no other debts, the Central Bank's ratios allow at most about AED 1.69 million over 25 years, tested at an illustrative 7.5%; a bank's own checks can lower it.
Can I get a mortgage pre approval for Abu Dhabi?
Yes. The Central Bank's limits apply across the UAE, and banks choose where they lend: Mashreq lends on homes in Dubai and Abu Dhabi, and Commercial Bank of Dubai's digital pre approval covers Dubai and Abu Dhabi for expats.
Sources
- CBUAE Rulebook: Regulations Regarding Mortgage Loans (LTV caps, 50% DBR and stress test, 25-year term, income multiples, own-funds deposit, independent valuation, fee schedule; checked 16 November 2026)
- CBUAE Rulebook: Consumer Protection Standards, Article 7 (Key Facts Statement, credit bureau check, stress-test and affordability summaries; checked 16 November 2026)
- CBUAE Rulebook: Decision No. 96/2019 amending Appendix 2 of Regulation No. 29/2011 (home loan fee caps; checked 16 November 2026)
- Commercial Bank of Dubai: Mortgage straight-through pre-approval FAQ (PDF) (definition, eligibility, locations, approved developers for off-plan, 60-day validity; checked 16 November 2026)
- Commercial Bank of Dubai: Key Facts Statement, mortgages, version 31 October 2025 (PDF) (minimum income, pre approval, processing, revalidation and valuation fees; checked 16 November 2026)
- Commercial Bank of Dubai: Home Loan (eligibility, documents; checked 16 November 2026)
- Emirates NBD: Apply for a home loan (minimum salary, age, documents, fees, joint borrowers; checked 16 November 2026)
- Emirates NBD: Key Facts Statement, home loan, 02/2026 (PDF) (processing and valuation fees, processing time; checked 16 November 2026)
- Mashreq: Home Loans (minimum income, locations, pre approval documents, age; checked 16 November 2026)
- Mashreq: Key Facts Statement, home loans, revised 19 June 2026 (PDF) (pre approval, processing and valuation fees, off-plan completion; checked 16 November 2026)
- ADCB: Standard mortgage loan (pre approval, documents; checked 16 November 2026)
- ADCB: Mortgage Key Facts Statement, February 2026 (PDF) (processing fees; checked 16 November 2026)
- Dubai Islamic Bank: Home Finance (First Step Qualified; checked 16 November 2026)
- Etihad Credit Bureau: FAQs (personal credit report price and coverage; checked 16 November 2026)
- Dubai Land Department: Mortgage registration (registration fees; checked 16 November 2026)
Pre approved and ready to look? Talk to an agent about homes within your budget, or browse properties for sale.