The tax on rental income in UAE law is Corporate Tax, and an individual who lets a home, office or shop on an ordinary lease without a licence pays none of it, however much rent comes in. Companies, and individuals who let through a licence such as a Dubai holiday-home permit, can owe 9% on taxable income above AED 375,000; a licensed individual is inside Corporate Tax only once that business turns over more than AED 1 million in a calendar year. VAT is a separate test: rent on a home is normally exempt, and rent on an office or shop carries 5% when the landlord is registered for VAT.
- Individual, ordinary lease registered on Ejari: no Corporate Tax and no Corporate Tax registration, whether you live in the UAE or abroad.
- Individual with a holiday-home permit or a licensed property business: Corporate Tax once that business turns over more than AED 1 million in a calendar year, at 0% on the first AED 375,000 of taxable income and 9% above.
- Company, whether mainland, free zone or foreign: inside Corporate Tax, on the rent and on the profit from a sale.
- VAT: a home's rent is exempt on a lease over six months or to a tenant with an Emirates ID; offices and shops carry 5%.
The rules come from Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses (the Corporate Tax Law), Cabinet Decision No. 49 of 2023 on natural persons, and the Federal Tax Authority's (FTA) guide Real Estate Investment for Natural Persons (CTGREI1, October 2024). The FTA says its guides aren't legally binding, and tax turns on facts, so confirm your own case with a registered tax agent.
Who pays tax on rental income in UAE law, and how much?
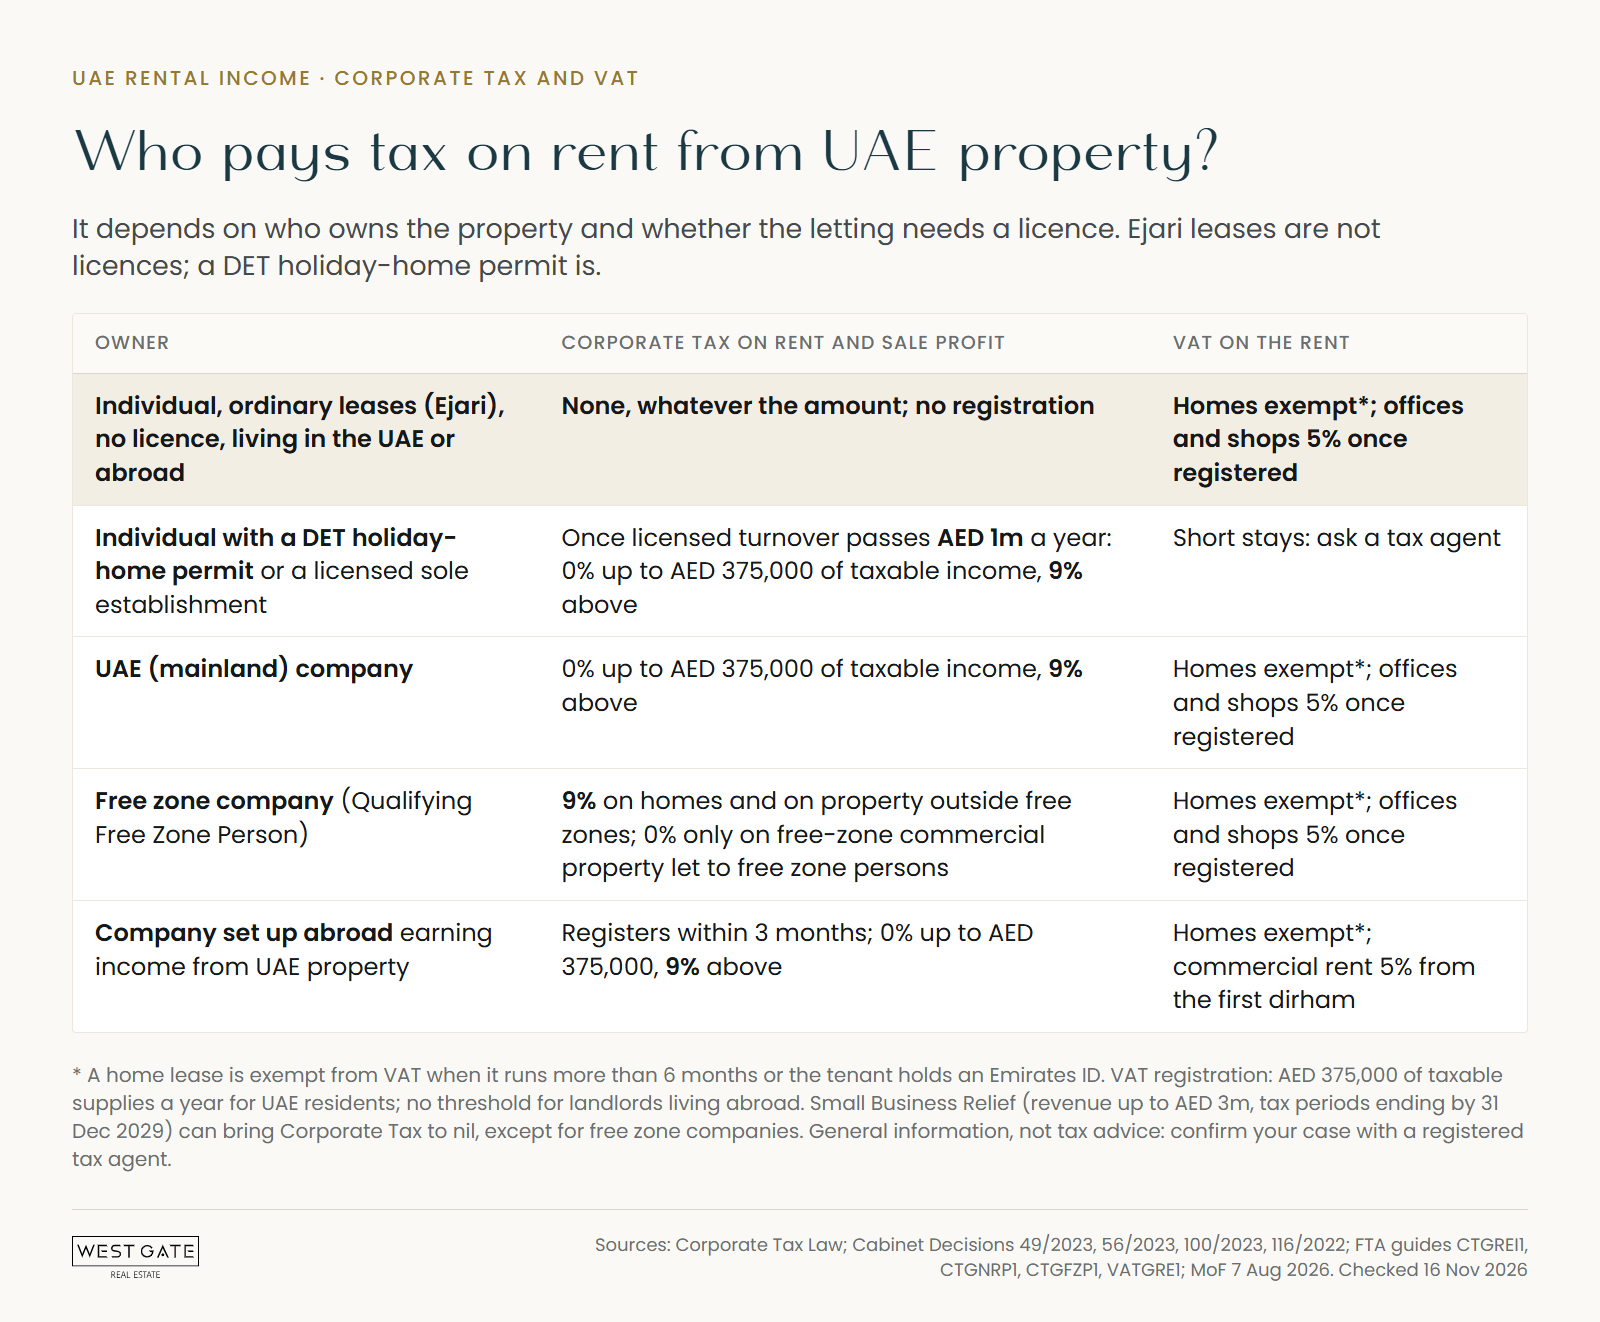
It depends on the owner, not the property. Individuals letting on ordinary leases are outside Corporate Tax. Individuals letting through a licence, UAE companies, free zone companies and companies set up abroad that own UAE property are inside it, mostly at 0% on the first AED 375,000 of taxable income and 9% above. VAT follows the property type instead.
| Who owns the property | Corporate Tax on rent and on a sale profit | القاعدة |
|---|---|---|
| Individual letting on ordinary leases (Ejari), no licence, living in the UAE or abroad | None, whatever the amount; no registration | Cabinet Decision No. 49 of 2023 Arts 1, 2(2)(c), 2(3); CTGREI1 §4.2, Example 7 |
| Individual letting holiday homes under a DET permit, or through a licensed sole establishment | Taxable once the licensed business turns over more than AED 1m in a calendar year: 0% up to AED 375,000 of taxable income, 9% above | Cabinet Decision No. 49 of 2023 Art 2(1); CTGREI1 §4.2.2.3, §4.2.4, Example 10 |
| UAE (mainland) company | 0% on the first AED 375,000 of taxable income, 9% above | Corporate Tax Law Arts 3, 20; Cabinet Decision No. 116 of 2022 Art 2 |
| Free zone company (Qualifying Free Zone Person) | 9% on income from homes, hotels and serviced apartments, and from property outside a free zone; 0% possible only on commercial property in a free zone let to free zone persons | Corporate Tax Law Art 3(2); Cabinet Decision No. 100 of 2023 Art 6; Ministerial Decision No. 265 of 2023 Art 2(2)(e) |
| Company set up abroad earning income from UAE property | Must register; 0% on the first AED 375,000 of taxable income, 9% above | Cabinet Decision No. 56 of 2023 Arts 2, 4; FTA guide CTGNRP1 §9 |
The 0% band and the 9% rate are set by Article 3 of the Corporate Tax Law and Cabinet Decision No. 116 of 2022. On taxable income of AED 500,000, the tax is 9% of the AED 125,000 above the band: AED 11,250.
Do individuals pay tax on rental income in Dubai?
No, as long as the letting is “Real Estate Investment”: renting, leasing, sub-leasing or selling land or property in the UAE without a licence and without needing one. Cabinet Decision No. 49 of 2023 keeps that income outside Corporate Tax whatever the amount, for UAE residents and non-residents alike, and an owner with no other taxable business doesn't register.
The FTA's guide applies this to homes, offices, shops, warehouses and parking, whoever the tenant is and however many units you own (CTGREI1 §4.2.2). Registering a lease on Ejari doesn't make it a licensed business: the guide calls Ejari, and Abu Dhabi's Tawtheeq, administrative records, not licences (§4.2.2.3).
Using an agent changes nothing. If a licensed property manager finds tenants, registers the contracts and collects the rent while you stay the landlord on the lease, the rent is still yours and still excluded (§4.2.3, Example 5). The same goes for letting a whole building to a licensed hotel operator for a fixed yearly sum when you take no part in running the hotel (Example 4a). Co-owners each look at their own share (§4.5).
The other side of the exclusion: costs linked to that rent can't be deducted, and a loss gets no relief (§4.3). Letting your first unit? Our guide on how to rent your property in Dubai covers the steps from listing to Ejari.
When does a landlord pay Corporate Tax in the UAE?
When the letting needs a licence. The FTA treats a Dubai Department of Economy and Tourism (DET) permit to let holiday homes as a licence, and the same goes for a sole establishment licensed to manage property. That income counts towards the AED 1 million turnover test; above it, the owner registers and pays 9% on taxable income over AED 375,000.
Needing a licence and not having one doesn't help: the guide treats the activity as a business anyway (§4.2.2.4). Only the licensed lets count. In the FTA's Example 10, an owner with 16 Dubai flats lets 14 as holiday homes under DET permits and 2 on Ejari leases: the 14 are taxable business income, the 2 stay outside Corporate Tax, and shared costs are split on a fair basis.
If a licensed holiday-home operator holds the permits and runs the stays, your position turns on the contract; the guide's agent and hotel-lease examples (Examples 5 and 4a) are the closest, so ask a tax agent. Our holiday home permit guide covers the permit itself.
Small Business Relief can bring the bill to nil. A resident whose revenue is AED 3 million or less in the tax period and in every earlier one may elect to be treated as having no taxable income (Corporate Tax Law Article 21; Ministerial Decision No. 73 of 2023 Article 2). The relief was due to stop with tax periods ending on 31 December 2026; on 7 August 2026 the Ministry of Finance announced Ministerial Decision No. 131, which extends it to tax periods ending on or before 31 December 2029.
- Tax period: for an individual, the calendar year (FTA guide CTGTNP1 §3.12).
- Register: by 31 March of the year after licensed turnover passed AED 1 million; three months after meeting the test for a non-resident (FTA Decision No. 3 of 2024 Article 5).
- File and pay: within nine months of the end of the tax period, so by 30 September for a calendar year (Corporate Tax Law Articles 48 and 53).
How is rental income taxed when a company owns the property?
A company is a separate taxpayer, so its rent and its profit on a sale are taxable income: 0% on the first AED 375,000 and 9% above for a UAE company. A free zone company pays 9% on most property income, and a company set up abroad that earns income from UAE property must register for Corporate Tax in the UAE.
UAE company. The FTA's Example 13 is an individual whose own company owns a commercial building: the company is taxed on the rent, and dividends it pays the individual are personal investment income, outside Corporate Tax (CTGREI1 §4.6). A UAE company with revenue of AED 3 million or less can elect Small Business Relief if it meets the other conditions.
Free zone company. For a Qualifying Free Zone Person, only income from commercial property inside a free zone, from dealings with other free zone persons, can be qualifying income at 0%. Income from homes, hotels and serviced apartments in a free zone is taxed at 9% (Cabinet Decision No. 100 of 2023 Article 6), and owning or exploiting property outside a free zone is an excluded activity, so its income isn't qualifying either (Ministerial Decision No. 265 of 2023 Article 2(2)(e); FTA guide CTGFZP1 §8.3). These companies can't elect Small Business Relief (Ministerial Decision No. 73 of 2023 Article 3).
Company set up abroad. A foreign company has a “nexus” in the UAE once it earns income from UAE land or buildings, including rent, sub-letting and a sale (Cabinet Decision No. 56 of 2023 Article 2). It must register within three months of the nexus arising (FTA Decision No. 3 of 2024 Article 4) and pays 0% on the first AED 375,000 of taxable income and 9% above (CTGNRP1 §9). The nexus rule doesn't apply to individuals.
Moving property between yourself and a company mainly to save tax can be undone by the FTA under the general anti-abuse rule (Corporate Tax Law Article 50; CTGREI1 §5), and leases or management contracts with your own company must be on arm's length terms (§4.3.2).
Is there VAT on rental income in the UAE?
On some rent. Leasing a home is exempt when the contract runs more than six months or the tenant holds an Emirates ID, and a new home's first lease or sale within three years of completion is zero-rated. Rent on offices, shops and warehouses carries 5% VAT, charged by a landlord who is registered for VAT or required to register. Who owns the property doesn't change these rules.
| المالك | Must register for VAT when | القاعدة |
|---|---|---|
| Living in the UAE | Taxable supplies, such as commercial rent at 5%, passed AED 375,000 over the last 12 months or will in the next 30 days | FTA, Registration for VAT |
| Living abroad | From the first taxable supply: no threshold, and a registered tenant can't account for the VAT instead | FTA real estate VAT guide VATGRE1 §11.3 |
Article 43 of the VAT Executive Regulation reads the lease term from the contract, ignoring renewal options and early-exit rights. A short holiday-home stay fails the six-month test, so the exemption then turns on the guest holding an Emirates ID; neither the law nor the FTA's real estate guide names holiday homes, so ask a tax agent before taking bookings. Hotel and serviced apartments aren't residential for VAT (Article 37); our guide to VAT on property in Dubai has the detail.
The 5% housing fee on a DEWA bill isn't VAT on rent: it is a Dubai Municipality fee, explained in our housing fee guide.
Is there capital gains tax on Dubai property?
Not for an individual selling without a licence. Selling land or property counts as Real Estate Investment, so the profit stays outside Corporate Tax: in the FTA's Example 7, a home bought in 2023 for AED 3,000,000 and sold in 2024 for AED 3,400,000 leaves the AED 400,000 profit untaxed. A company's profit on a sale is taxable income.
Sales made through a licensed property business are business income like any other. For a UAE company, Article 20 of the Corporate Tax Law builds taxable income from its accounts, so the gain is taxed with the rent at 0% and 9%. A company that owned a property before its first tax period, carried at historical cost, can elect to leave out the gain built up before that period (Ministerial Decision No. 120 of 2023 Article 2). Our breakdown of selling property in Dubai fees lists the costs of the sale itself.
Do you pay tax on Dubai rental income in your home country?
You may: the UAE's rules decide only the UAE's tax. Your home country can tax Dubai rent that the UAE leaves alone, depending mainly on where you are tax resident. Two examples from official pages show how residents report it; check your own country's rules before the first rent arrives.
- United Kingdom: if you're UK resident, you'll normally pay UK tax on foreign income, including rent from overseas property, reported in Self Assessment, unless you're eligible for Foreign Income and Gains relief (HM Revenue and Customs, “Tax on foreign income”).
- India: residents report all income from outside India in Schedule FSI of the return and list property abroad, with its income, in Schedule FA Table C; ITR-1 and ITR-4 can't be used (Income Tax Department guide, March 2026). More in our guide to buying property in Dubai for Indians.
What should landlords check before letting?
Six facts decide your tax position: who holds the title deed, whether any letting needs a licence, licensed turnover against AED 1 million, commercial rent against the VAT threshold, where you are tax resident, and whether your records show which income is which. Settle them before the first lease, not at the first return.
- Owner: you, a licensed sole establishment, a UAE company, a free zone company or a company abroad.
- Licence: a DET holiday-home permit or a property licence moves those lets into Corporate Tax.
- Turnover: licensed income against AED 1 million in the calendar year; ordinary leases don't count.
- VAT: commercial rent against AED 375,000 a year if you live in the UAE; from the first dirham if you don't.
- Home country: where you are tax resident, and how it treats foreign rent.
- Records: leases, Ejari certificates and permits that show which unit earns what.
Our property management team handles leases, Ejari and rent collection for owners in Dubai; contact us about a specific property. For the tax position on your own income, a registered tax agent or the FTA has the final word.
الأسئلة المتكررة
Is rental income taxable in the UAE?
Not for an individual who lets property on ordinary leases without a licence: Cabinet Decision No. 49 of 2023 keeps that income outside Corporate Tax whatever the amount. Companies, and individuals letting through a licence such as a holiday-home permit, can owe 9% Corporate Tax on taxable income above AED 375,000.
Do I pay tax on rental income in Dubai if I live abroad?
Not in the UAE if you own in your own name and let without a licence: the exclusion covers residents and non-residents. The country where you are tax resident may tax it; UK residents, for example, normally pay UK tax on rent from overseas property.
Do holiday home owners in Dubai pay Corporate Tax?
They can. The FTA treats a DET holiday-home permit as a licence, so that rent counts towards the AED 1 million turnover test. Above it the owner registers and pays 9% on taxable income over AED 375,000, unless they elect Small Business Relief, open to revenue up to AED 3 million.
How do I pay tax on rental income in the UAE?
Most individual landlords have nothing to file or pay. Licensed landlords and companies register with the FTA, file a Corporate Tax return and pay within nine months of the end of the tax period; an individual registers by 31 March of the year after licensed turnover passed AED 1 million.
Is there capital gains tax on property in Dubai?
Not for an individual selling without a licence: the profit is Real Estate Investment income, outside Corporate Tax. A UAE company's gain is taxable income, at 0% on the first AED 375,000 and 9% above.
Is there VAT on residential rent in the UAE?
Not when the lease runs more than six months or the tenant holds an Emirates ID (VAT Executive Regulation Article 43). Rent on offices and shops carries 5% VAT when the landlord is registered or required to register.
Does a foreign company that owns Dubai property pay UAE Corporate Tax?
Yes, if it earns income from the property. Rent or a sale gives it a nexus in the UAE under Cabinet Decision No. 56 of 2023: it registers within three months and pays 0% on the first AED 375,000 of taxable income and 9% above.
مصادر
- Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses, as amended (FTA, PDF): Articles 3, 11, 20, 21, 48, 50, 53
- Cabinet Decision No. 49 of 2023 on natural persons (FTA, PDF): Articles 1 and 2
- FTA guide CTGREI1, Real Estate Investment for Natural Persons, October 2024 (PDF): §3 to §5, Examples 4a to 13
- FTA guide CTGTNP1, Taxation of Natural Persons (PDF): §3.11, §3.12
- Cabinet Decision No. 116 of 2022 (FTA, PDF): the AED 375,000 band
- Cabinet Decision No. 56 of 2023 on non-resident nexus (FTA, PDF) and FTA guide CTGNRP1 (PDF): §9
- Cabinet Decision No. 100 of 2023 (FTA, PDF), Ministerial Decision No. 265 of 2023 (PDF) and FTA guide CTGFZP1 (PDF): §8
- Ministerial Decision No. 73 of 2023 on Small Business Relief (FTA, PDF) and Ministry of Finance: relief extended to 31 December 2029 (7 August 2026)
- Ministerial Decision No. 120 of 2023 on transitional rules (FTA, PDF): Article 2
- FTA Decision No. 3 of 2024 on registration timelines (PDF): Articles 4 and 5
- FTA: Real Estate VAT Guide VATGRE1 (PDF): §2.3, §3.3, §6.2, §11.3; VAT Executive Regulation, as amended to 2026 (PDF): Articles 37 and 43; FTA: Registration for VAT
- GOV.UK (HMRC): Tax on foreign income; Income Tax Department: guide to Schedules FSI, TR and FA (PDF)
Checked on 16 November 2026 We update this page when the FTA or the Ministry of Finance publish a new guide or decision on real estate income, Small Business Relief or VAT on leases.